Analysis Plan · siting
How to Choose a Data Centre Location: Five Maps, Two Permanent
Siting a data centre means overlaying five constraint maps. Three are dissolving this decade. Two never will, and they point to a place we know.
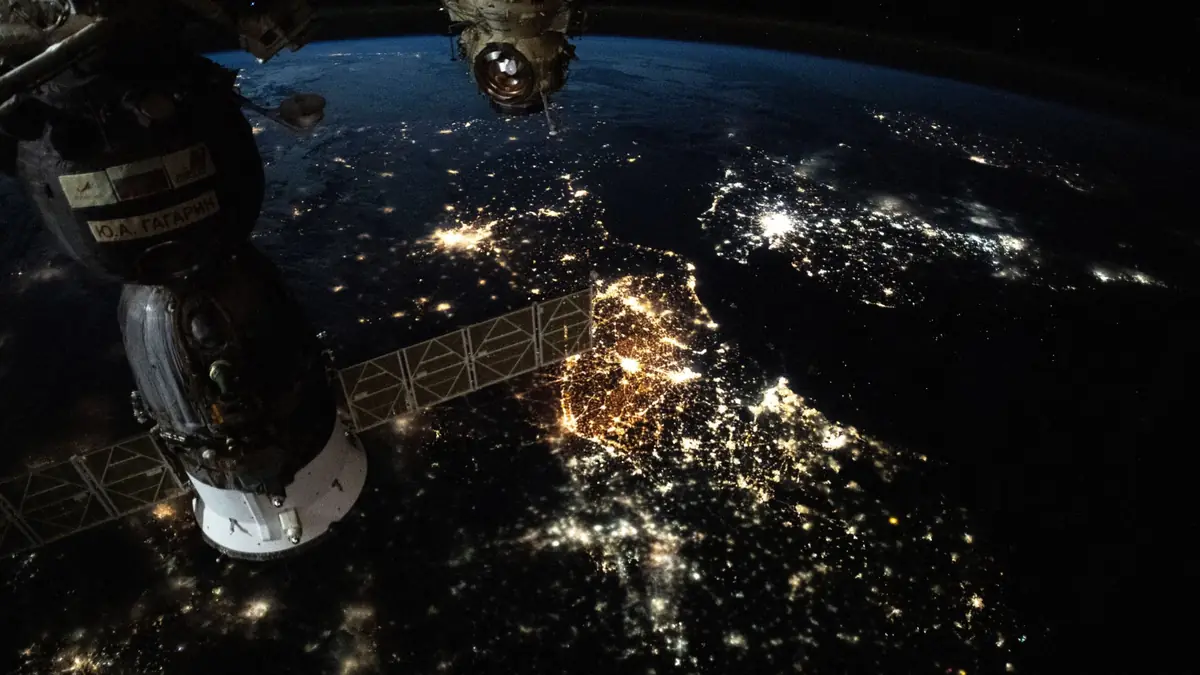
You can put up a hyperscale data centre in eighteen months. Getting it connected to the European grid takes seven to ten years, and thirteen at the worst nodes. Projects that fail here usually fail because they picked a field they couldn’t energise.
So siting is an overlay. You take five maps of the same continent, put them on top of each other, and look for the places where all five agree. Each map deletes most of Europe, and what’s left is a shortlist you can count on one hand.
The order you apply them in decides whether you waste two years. There’s a second question underneath, and it should shape anything you’re planning past this decade: engineering is dissolving three of these constraints right now, and the other two will stay exactly where they are.
Map one: ground somebody will insure
You’re asking an investor to put somewhere between a hundred million and several billion euro into one fenced compound and leave it there for twenty years. The land has to be boring in a very particular way.
Three things rule a site out on the spot. Geopolitical exposure, meaning any jurisdiction where the rules around your asset can change faster than you can depreciate it. Seismic hazard, where the design acceleration pushes you into structural work that adds cost and not one megawatt of capacity. And flood, where people are still sloppiest. The screen that matters is the 1-in-1000 line on the climate-adjusted maps (the 1-in-100-year line is too generous), and it has to cover pluvial as well as fluvial flooding. Plenty of sites are dry on the river map and sit under drainage that was sized for a different century.
The quickest proxy for all three is whether anyone will insure it. If underwriters won’t quote twenty years on the shell and the contents without a war exclusion or a flood carve-out, you have your answer.
Regulatory stability belongs on this map too. A site can be seismically dead, hydrologically dry and politically calm, and still find its host has changed its mind: in August 2026, Texas ordered its grid operator to audit the same data-centre industry it had spent a decade courting.
Map two: close to the business you serve
Most siting exercises treat this map as a preference, ranked below cost and land price. I’d put it near the top, because it’s the one map on this list that outlives every technology shift.
It has two halves. The first is latency. A data centre exists to serve somebody, and for most enterprise workloads that somebody is a business with users, branches and machines in a specific place. Light in glass does about 200,000 km/s, which works out at roughly 1 ms per 100 km each way before anything touches the packet, and real fibre routes are never straight lines. For trading, industrial control, or anything with a person waiting on the other end, that budget goes fast, and no contract can buy it back.
The second half is sovereignty, and it’s the harder one. A European bank, hospital or manufacturer often can’t put certain data outside a defined jurisdiction, and increasingly won’t put it anywhere a foreign authority could compel disclosure. That’s why customers ask where the building physically stands before they ask what a rack costs. They treat data the way a bank treats deposits: it has to be safe here, under rules they recognise.
That’s why data centres cluster around commercial and industrial cores instead of the cheapest field two hundred kilometres out.
Map three: power you can actually draw
This is the map that kills the most individual sites. You can negotiate almost everything else on this list. You can’t negotiate electrons.
A substation nearby is necessary and nowhere near sufficient. What you need is a firm connection offer for a stated capacity, on a network with the upstream headroom to deliver it, which means transmission as well as distribution. A 400 kV line overhead is scenery if everyone ahead of you in the queue has already claimed its capacity.
Across the EU, connection waits run from two to ten years depending where you are, and seven to ten in the markets everybody wants. Those are the IEA’s own figures. Ireland made the arithmetic explicit: the CRU blocked EirGrid from connecting new data centres in greater Dublin, a freeze that ran towards 2028 before reopening in December 2025 on condition that new load bring 80% of its energy from newly built Irish renewables. Data centres, overwhelmingly sited around Dublin, already took about a fifth of the country’s electricity. A grid operator was telling the market the arithmetic doesn’t close.
So what you’re buying is powered land: a plot with a signed connection agreement and a date on it. The market has repriced accordingly. JLL puts prime powered land in Europe’s five biggest markets at €2.26 million per megawatt, up 82% from €1.24 million in 2021, and its same mid-2026 figures put the premium at 2.3× over secondary sites and 4× over tertiary ones. The money pays for a place in a queue.
Source: JLL, EMEA Data Centre Report (mid-2026), jll.com — retrieved 2026-09-18
Map four: fibre, and what the building is for
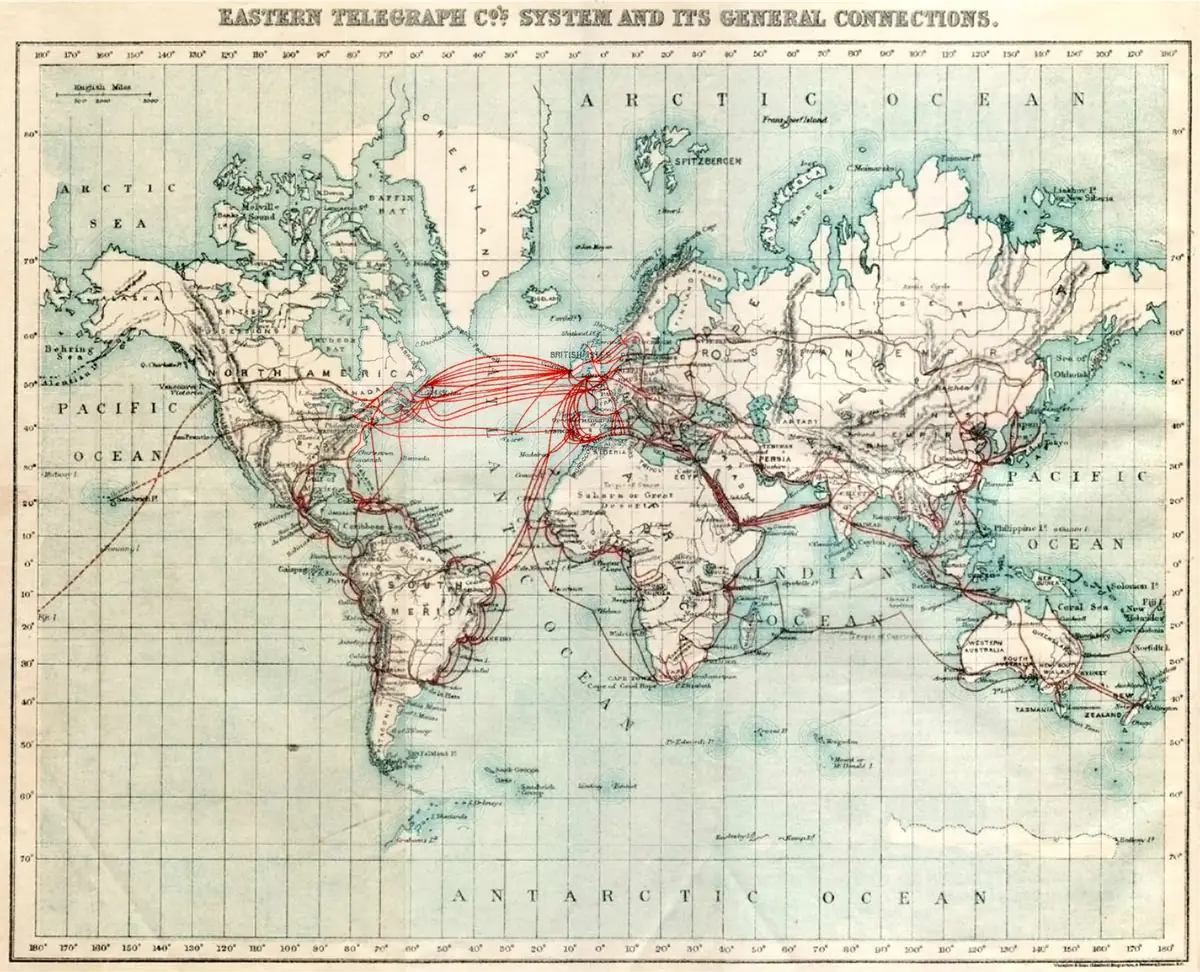
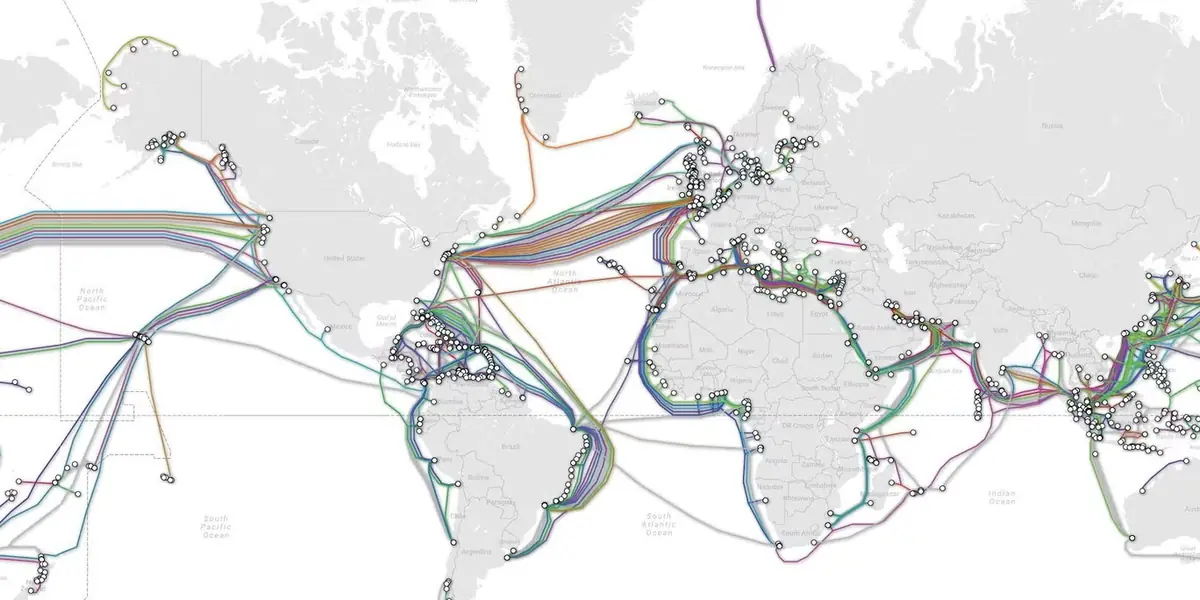
Put the subsea cables and the terrestrial long-haul routes on the same sheet and the pattern is uneven. Capacity comes ashore at a handful of coastal points, and inland the long-haul follows old rights of way (railways, motorways, pipelines), so it runs in corridors.
Those corridors are older than the industry using them. Below are two maps of the same planet, 125 years apart: the Eastern Telegraph Company’s chart of the world’s cable routes in 1901, and every submarine cable in service today. Almost everything about the technology changed, and the routes stayed put: the same Atlantic crossings, the same Mediterranean corridor through Gibraltar and Suez, the same run down the west coast of Africa, the same choke point at the Red Sea. Cable follows the cheapest seabed and the friendliest shore, and neither has moved.

How much this map matters depends entirely on what the building does, and this is where people weight it wrong.
For a colocation business, being on those routes is the product. Customers are buying cross-connects: the ability to reach carriers, clouds and each other inside your building, so a colocation hall off the fibre map sits empty. For a training campus the maths is much looser. A cluster chewing through a run for three weeks needs enormous internal bandwidth and little egress, which is why training load is the workload drifting towards wherever the power happens to be. Work out which building you’re siting before you decide how much this map counts.
Map five: the people who keep it running
The last map doesn’t exist in any dataset, and it kills more projects than anyone admits.
A data centre needs people. It needs an airport within a sane drive, because vendors, auditors and customers turn up in person, and a city close enough that the people you hire will stay. Most of all it needs an ecosystem: electrical contractors who have commissioned switchgear of this class before, mechanical firms who have run chilled water at scale, controls integrators, a spares chain, and enough of each that no single vendor can hold your commissioning date hostage.
The first building in a region pays to build that ecosystem. The tenth gets it for free. If you’re the first, be honest with yourself about the schedule.
The rule: screen in this order, and know which screens expire
Run the maps in order of how fast a failure ends the conversation. A site has to clear all five, and the first failure stops the work. There’s nothing to negotiate.
The last column is the one to plan against. It says whether a screen is a fact about this decade or a fact about the world.
| Order | Screen | Pass condition | Fails if | Permanent? |
|---|---|---|---|---|
| 1 | Power | Firm connection offer, stated MW, contractual energisation date inside the investment window | Queue position only, or capacity “expected” without a signed offer | No — loosening from about 2030 |
| 2 | Safe ground | Outside the 1-in-1000 flood extent on climate-adjusted maps, low seismic design category, twenty years insurable with no war or flood carve-out | Any underwriter exclusion, or rules that can change inside the depreciation period | Yes |
| 3 | Proximity to demand | Inside the latency budget of the users served (about 1 ms per 100 km of fibre, each way), in a jurisdiction the customer’s data may legally sit in | The data would land under a legal regime the customer can’t accept, at any price | Yes |
| 4 | Connectivity | Colocation: two or more diverse long-haul routes in physically separate ducts. Training: adequate egress, no single path | One route, or two routes sharing a duct or a bridge crossing | No — loosening now |
| 5 | Ecosystem | International airport inside about 90 minutes, commissioning contractors with class-relevant references in region, competing vendors on every critical trade | Single-source on any critical trade, or a talent pool you’d be the only employer in | No — loosening slowly |
Power goes first because it fails fastest, and it’s also the constraint most likely to be gone in ten years. Safe ground and proximity to demand rarely kill a site on day one, yet they’re the only two that will still be standing once everything else here has been engineered away.
Three of the five are dissolving
Each of the temporary constraints has a technology aimed squarely at it, and the three are at wildly different stages.
Power is decoupling from the grid. Instead of waiting in a queue, operators are contracting their own nuclear capacity direct from the plant: Microsoft’s 835 MW deal with Constellation to restart Three Mile Island Unit 1, Meta’s 1,121 MW deal for Constellation’s Clinton plant, Amazon’s 1,920 MW purchase from Talen Energy’s Susquehanna plant (on top of its earlier $700 million bet on X-energy’s small modular reactors), and Google’s 500 MW order from Kairos Power. That’s 4.4 GW across four deals alone, and across roughly a dozen like them, U.S. hyperscalers had more than 10 GW of nuclear capacity under contract within about a year.
Source: Microsoft/Constellation (Sept. 2024, Three Mile Island Unit 1 restart), Google/Kairos Power (Oct. 2024, SMR fleet order), Meta/Constellation (June 2025, Clinton Clean Energy Center) and Amazon/Talen Energy (June 2025, Susquehanna PPA) — contracted or ordered capacity, not all of it generating yet. Retrieved 2026-09-18.
Be careful with this one, because it gets oversold constantly. What’s coming online first is restarted conventional plant. Crane is a 1970s pressurised water reactor being brought back from the dead, and the SMR orders are for first units around 2030 and fleets by 2035. This constraint loosens at the end of the decade, and it loosens in America before it loosens here.
Connectivity is becoming less positional. Low-earth-orbit constellations and each new mobile generation chip away at the penalty for sitting off a fibre corridor. That matters far more for training campuses and edge sites than for colocation, where the cross-connect is the product and a satellite link can’t replace a carrier-dense meet-me room.
Operations need fewer local hands. Automated routine maintenance, remote-hands robotics and lights-out running all weaken the fifth map, the one tying sites to existing hubs. It’s the least mature of the three and the one I’d discount hardest, but it’s directionally real, and if it arrives properly it would widen the map more than either of the others.
No roadmap anywhere moves a fault line, drains a floodplain, or makes an untrustworthy jurisdiction trustworthy. Nothing repeals the speed of light either, and nothing is going to talk a regulated European institution into accepting that its data may sit under a foreign compulsion regime. Engineering can’t touch maps one and two.
Why this points somewhere obvious
Three constraints get engineered away over the next decade and two stay. So the places that win in the long run are the ones that score well on the two nobody can fix, and badly (for now) on the three everybody is fixing.
That is a description of Europe.
Most of its northern and central landmass is seismically quiet, and it is politically stable over the horizons this kind of money needs. It also holds one of the largest concentrations of regulated industrial and financial demand anywhere: the banks, manufacturers, hospitals and public institutions whose data is subject to exactly the sovereignty rules that make map two binding.
Europe’s weaknesses are the three temporary ones: the grid queues are the worst in the developed world, power is expensive, permitting is slow. The market is already routing around them. CBRE’s mid-2026 figures show only 37% of the roughly 700 MW of new European capacity added that quarter went to Frankfurt, London, Amsterdam, Paris or Dublin. The rest went to Spain, Italy, Poland and the Nordics, where the first screen still passes.
So the European shortlist is short today because of the three constraints that are dissolving. Fix the grid and Europe stops being one option among several for European data. On the only two maps that will still matter in 2040 it’s the obvious answer, and the schemes to float data centres offshore more or less admit it: they’re trying to escape an overlay that, for anyone who actually has to comply with something, can’t be escaped.